Financial Architecture
Pension reform: We need to discuss a longevity system for the 21st century
The debate surrounding pensions is usually reduced to whether retirement age should be raised. But the underlying issue is different: we are living longer, fewer children are being born, and the institutions financing retirement were designed for a demographic reality that no longer exists.
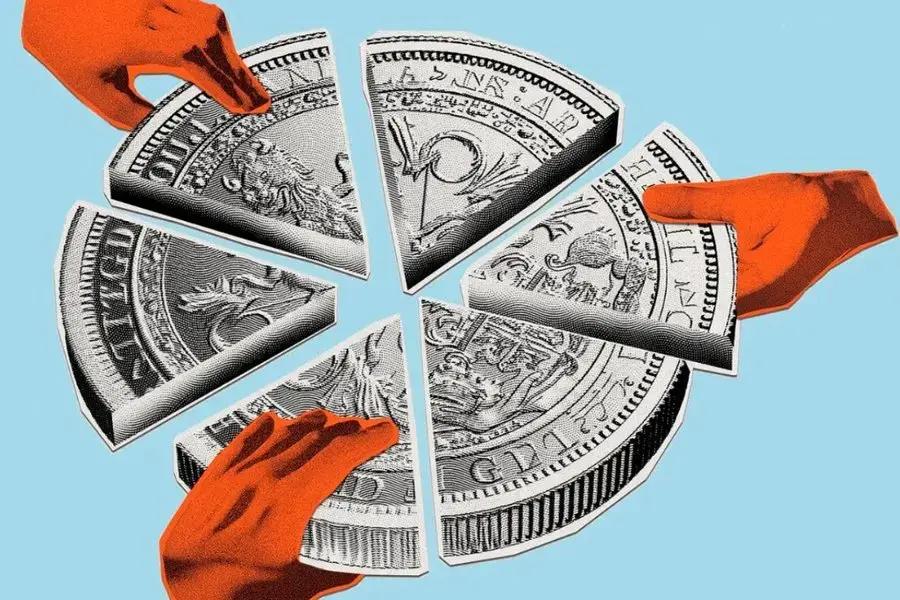
Every time pension systems are discussed, the same debate arises: whether or not retirement age should be increased. It is a politically uncomfortable and socially sensitive conversation that typically triggers immediate reactions. Yet, behind that discussion lies a much more important question that is rarely asked. Does it still make sense to organize retirement using rules designed for a demographic reality that no longer exists?
The challenges facing pension systems are not unique to any single country. From Europe to Latin America, governments of diverse political stripes face the same tension: fewer births, rising life expectancy, and a growing number of years of benefits to fund. Added to this are additional challenges, especially in our region, such as labor informality, low contribution density, and increasingly fragmented career paths. The pension crisis is not a financial problem; it is the consequence of a demographic shift that has transformed the rules of the game.
Throughout much of the 20th century, retirement systems were designed for societies where people lived much shorter lives. The logic was relatively simple: a stage of education, a long working life, and a relatively short retirement period. Today, the reality is different. Millions of people reach the age of 60 or 65 with decades of life ahead of them. In many cases, they enjoy good health, have the capacity to keep working, and want to continue participating actively in the economy and society. We are still using institutions from the last century to manage lives characteristic of the 21st century.
A few days ago, during a visit to the Panama Canal, I heard an explanation that perfectly sums up this challenge. When it was inaugurated, the canal represented one of the greatest engineering innovations of its time. However, over the decades, ships grew larger, global trade changed, and that infrastructure ceased to meet new needs. The solution was not to close the canal or deny reality. The solution was to invest, expand it, and adapt it to build a canal prepared for the 21st century. The problem wasn't the canal. The problem was that the world had changed.
Something similar is happening with our retirement systems. The question should not solely be how we finance more years of retirement. We should also ask ourselves how we build societies prepared for longer lives. Because simply raising the retirement age solves nothing if people stop getting hired at 50, if they face barriers to updating their skills, or if the labor market continues to push out talent due to age. Extending the retirement age without extending employability simply shifts the problem from one place to another.
That is why the pending conversation goes far beyond pensions. It involves discussing financial education and long-term savings. It means designing systems that help people prepare for longer, less linear career paths. It requires promoting continuous learning, combating ageism in organizations, and creating environments that enable people to work longer in a healthy and productive manner. It also means recognizing that women face particular challenges, as they generally live longer, more frequently interrupt their careers to take on caregiving responsibilities, and consequently often reach old age with fewer accumulated resources.
The discussion about retirement age will remain necessary. But focusing the entire debate on that point is like arguing about the size of a lock gate when what needs modernizing is the entire canal. The real question is not at what age people should retire. The real question is how we design a society prepared so that those who want and need to keep working can do so under dignified, productive, and sustainable conditions.
Longevity is one of humanity's greatest achievements. Yet, we continue trying to manage it with structures designed for another time. Perhaps the conversation nobody wants to have is precisely the most urgent one: not how we reform a pension system, but how we build a longevity system capable of responding to the realities of the 21st century. Because the world has already changed. And our institutions will have to do so as well.
Interested in this analysis?
Get The Shift Signals every month, or access membership for research, reports, and in-depth learning.